Retail Media Concepts
The Future of Retail Media: Trends, Forecasts and How Retailers Become Media Networks
Posted on
November 20, 2025
|
Last updated:
November 12, 2026
Table of contents
The retail media edge, before everyone else has it.
The future of retail media is slower growth that rewards proof: it stays one of advertising's fastest-growing channels through 2028, and the retailers that gain share will be the ones that prove incremental sales to brands. Growth is easing and concentrating in the two largest networks, so for every other retailer, marketplace and financial platform the next two years are about winning a larger share: proving incremental sales to brands, adding offsite, in-store and financial-data channels, and automating campaigns for the long tail of advertisers that big networks underserve.
The future of retail media is slower growth that rewards proof: it stays one of advertising's fastest-growing channels through 2028, and the retailers that gain share will be the ones that prove incremental sales to brands. Growth is easing and concentrating in the two largest networks, so for every other retailer, marketplace and financial platform the next two years are about winning a larger share: proving incremental sales to brands, adding offsite, in-store and financial-data channels, and automating campaigns for the long tail of advertisers that big networks underserve.
Osmos is a white-label retail media operating system for retailers and marketplaces. Its modular apps for onsite, offsite and in-store ads sit over your existing stack, so you can break your monetisation ceiling faster without rebuilding it.
Osmos already runs in-store retail media at chain scale: Mr DIY has more than 1,200 screens live across more than 1,100 stores on Osmos.
Last updated: November 2026 · Reviewed by Kunal Damgude, Growth and Product Marketing Manager
Retail media's first decade, traced in our complete guide to retail media evolution, was spent launching networks. From 2026 to 2028 those networks compete with one another for share, and the retailers that plan their measurement, channels and advertiser activation now are the ones still growing when the market slows.
What is the future of retail media through 2028?
The future of retail media is a larger market, past $200 billion worldwide in 2026, in which measurement quality, channel breadth and advertiser automation decide which networks win share as growth eases. WARC's Future of Commerce Media 2026 report forecasts that global retail media growth will fall to 11.5% in 2027 and to 9.8% excluding Amazon, the lowest rate WARC has recorded (The Desk, reporting WARC, August 2026). At that rate the category cannot lift every network at once, so a retailer now grows by winning brand budgets away from other networks.
Osmos groups the 2026 forecasts by the three requirements a retailer must meet to build a media network:
- Brands renew based on incremental sales. The networks that keep budgets measure that lift to a shared standard.
- Channels widen beyond the product page. Offsite audience extension, in-store screens and analog placements, and financial transaction data all become retail media inventory, which means new audiences reached through formats the retailer controls.
- Automation makes the long tail worth serving. AI-assisted campaign tools and managed services let a network activate hundreds of smaller advertisers that a human ad-ops team could never serve profitably.
The future of commerce media follows the same path at a wider scope. Commerce media is advertising offered by any company that facilitates transactions and holds first-party customer data, including retailers, banks, payment networks, and travel and delivery platforms. WPP estimated that commerce media would take 15.6% of global ad spend in 2025, ahead of the 14.6% spent on linear and connected TV combined (Digiday, December 2025). Osmos treats commerce media as the same operating problem as retail media: inventory, targeting, measurement and advertiser activation, run on first-party data.
How fast is retail media network growth, and where does the growth come from?
Retail media network growth stays positive through 2028 but slows each year, and Amazon and Walmart capture most of the new money. Osmos groups these forecasts by publisher and measurement scope: global or US, and retail media or the wider commerce media category.
| Publisher and scope | 2025 | 2026 | 2027 | 2028 | Forecast date |
|---|---|---|---|---|---|
| WARC, global retail media ad spend | Not reported | $200.4B | $223.4B (+11.5%; +9.8% excluding Amazon) | Not reported | August 2026 |
| WARC, retail media share of global ad investment | Not reported | Not reported | 15.2% | Not reported | August 2026 |
| WPP, global commerce media (mostly retail media networks) | $174.2B; 15.6% of global ad spend | +11.3% growth | Not reported | Not reported | December 2025 |
| EMARKETER, US retail media ad spend (as reported by Webtonic) | Not reported | $72.97B (+20.3%) | Not reported | Not reported | June 2026 |
| IAB, US commerce media spend growth (survey of 200+ brand and agency decision-makers) | Not reported | +13.6% (raised from +12.1% in January) | Not reported | Not reported | September 2026 |
| EMARKETER, US financial media network ad spend | $680M | Not reported | Not reported | $3.15B | June 2026 |
"Not reported" means the cited source did not publish a figure for that year. Sources: WARC via The Desk, WPP via Digiday, EMARKETER via Webtonic, IAB 2026 Outlook Study, September update, EMARKETER, State of Financial Media Networks 2026. Retrieved October 12, 2026.
For a retailer planning the next two years, the market is still large and growing. WARC puts global retail media at $200.4 billion in 2026, and the IAB raised its 2026 commerce media growth expectation by 1.5 points between January and September, on pace to grow about 10% faster than the overall US ad market. Outside Amazon, the global growth rate is easing toward single digits. US growth, at EMARKETER's +20.3% for 2026, runs well ahead of global growth because the largest US networks are still compounding.
Where the growth concentrates
Most retail media network growth goes to Amazon and Walmart. WARC, using Walrus Intelligence data, reports that Amazon captured 78% of US retail media spending in 2025, Walmart 7.5%, and all other networks combined 14.5% (The Desk, August 2026).
EMARKETER's figures point the same way on a different basis. As reported by Webtonic, EMARKETER estimates Amazon took over 75% of US retail media ad spend in 2025, and Amazon and Walmart together absorb roughly 89% of the category's new dollars in 2026 (Webtonic, updated October 2026).
The latest quarterly results from Amazon, Walmart and Instacart show the same pull toward scale:
- Amazon: advertising services revenue reached $19.8 billion in Q2 2026, up 26% from $15.7 billion a year earlier. In Amazon's words on the earnings call, the business was "generating $19.8 billion of revenue, up 26% year-over-year" (Andy Jassy, CEO, Amazon). The comparison is flattered by timing: Amazon's CFO noted that Prime Day moved into Q2 for most large countries this year, after falling in Q3 in 2025 (PPC Land, July 2026).
- Walmart: global advertising grew 38% in Q2 of fiscal 2027, with Walmart Connect in the US up 43% excluding VIZIO, building on $6.4 billion of global advertising revenue in fiscal 2026 (PPC Land, August 2026).
- Instacart: advertising and other revenue reached $297 million in Q2 2026, up 16% year over year and equal to 2.9% of gross transaction value (Instacart Q2 2026 results).
For a mid-market retailer, these numbers set the bar its network is measured against. Brands compare every network with Amazon and Walmart on the proof they get, the ease of buying and the audience they cannot reach elsewhere. A smaller network that is easy to buy, measures to a standard and reaches a distinct audience competes for the 14.5% and for the budgets brands hold back to diversify.
What does the retail media ecosystem look like in 2026?
The 2026 retail media ecosystem is a set of media owners, from retailers and marketplaces to banks and travel platforms, sitting on a shared layer of ad technology and measurement standards. Between 2024 and 2026 the set of retail media networks widened beyond retail: Chase Media Solutions and PayPal Ads launched in 2024 and Mastercard Commerce Media in 2025, while Amazon and Walmart kept most of the US spending. A retail media network (RMN) is the advertising business a retailer or marketplace runs on its own digital and physical properties, using its first-party shopper data to target ads and measure sales. Osmos builds the technology layer for that business as a white-label system the retailer runs under its own brand.
Osmos groups the ecosystem's media owners by the transaction data each one holds:
- Retailers and grocers monetize onsite search and browse placements, offsite audience extension and their store estates. Walmart Connect is the scaled example after Amazon.
- Marketplaces earn ad revenue from third-party sellers competing for visibility on the same product pages, which makes seller ads a core revenue line.
- Delivery and quick-commerce platforms monetize high-frequency baskets; Instacart's advertising line equal to 2.9% of transaction value shows how material this becomes.
- Financial institutions and payment networks turn card and account activity into a targeting layer for offers and ads, through financial media networks.
- Travel, mobility and other transaction platforms apply the same model to bookings and trips, which is why analysts increasingly use "commerce media" for the whole set.
Under the media owners sits the ad technology layer: ad servers and auction engines, self-serve buying tools, offsite activation, in-store booking and measurement systems. For the definition of commerce media and how it differs from retail media, see what commerce media is and how it differs. For the platform and network rankings, see the retail media evolution guide.
How do marketplaces monetize retail media differently from retailers?
Marketplaces monetize retail media mainly through seller competition, and traditional retailers mainly through brand budgets. Sellers run ads on a marketplace platform through self-serve tools, where each seller sets up, funds and optimizes its own campaigns. On a marketplace the advertiser base is the seller base: thousands of sellers each spend modestly and bid against one another for the same shopper on the same listing, which keeps auction density high even without large brand deals. A traditional retailer serves fewer, larger brand advertisers, often through negotiated packages and joint business plans.
Osmos sorts the marketplace differences by the ad technology each one requires:
- A long tail of sellers needs campaigns that are set up, funded and optimized without an account manager, so Osmos treats seller self-serve, wallets and billing as core marketplace infrastructure.
- Several sellers can offer the same product at once, so the ad engine needs live listing logic that points each ad to the seller currently holding the offer and to items in stock.
- A marketplace credits each sale to the specific product, seller and campaign, which calls for seller-level attribution.
- Marketplace targeting combines shopper behavior with seller-side catalog, price and fulfilment signals, a two-sided data layer richer than a single-catalog retailer's.
The model is spreading because marketplace commerce keeps growing inside large retailers: PPC Land reported Walmart's US marketplace net sales up 52% in Q2 of fiscal 2027 (PPC Land, August 2026). Many retailers now run a first-party catalog and a third-party marketplace side by side, which is why the question "retail media adtech for both retail and marketplace environments" keeps coming up. One ad engine has to serve brand packages and seller self-serve on the same pages, and Osmos's onsite retail media apps run Product Ads, display, video and custom formats from one ad server for both. For the mechanics of seller ad revenue in more depth, see how marketplaces earn ad revenue from seller competition.
How will offsite and programmatic change retail media budgets?
Offsite retail media will take a growing share of retail media budgets because it lets brands reach a retailer's audience beyond the retailer's own pages, while the retailer keeps the measurement link to sales. Offsite retail media is the activation of a retailer's first-party audiences on external channels such as social platforms, search, connected TV and the open web, with results reported back against the retailer's transactions.
The budget it draws on is mainly open-web programmatic display. Display bought on inferred audiences is exactly what a retailer's purchase-based audiences replace, so that line comes under pressure first. Retail media reaches shoppers at the point of purchase, while connected TV and social video add upper-funnel attention and reach, which is why brands increasingly put them in the same plan. For a retailer, the practical order is to extend into the channels brands are already funding, social and video first, and to treat open-web display as the secondary layer.
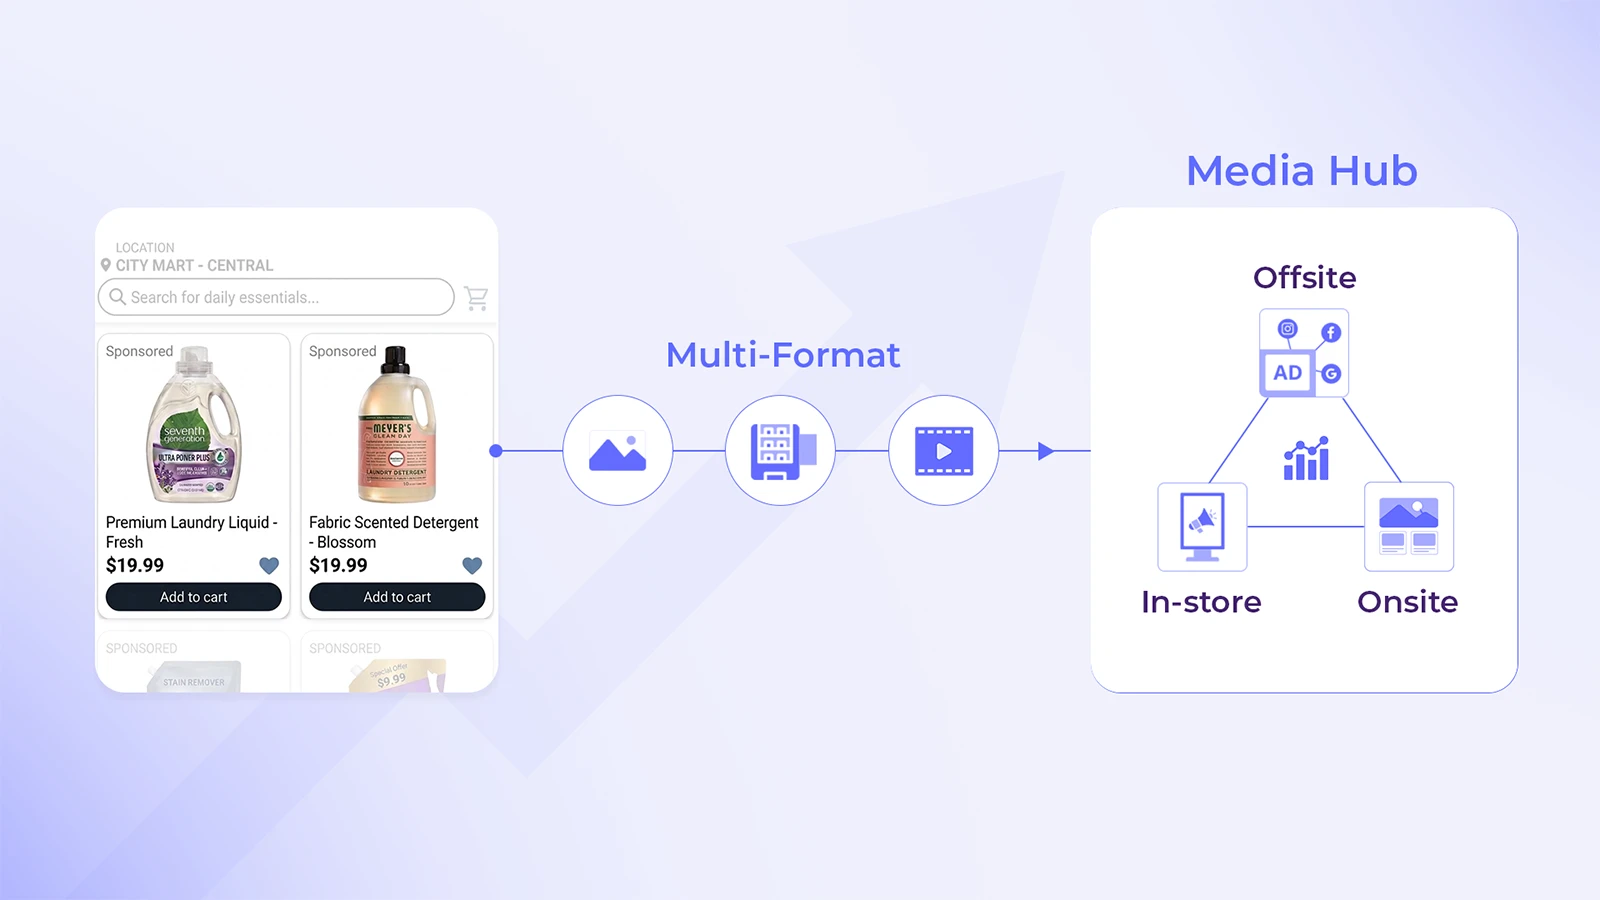
Offsite also changes the commercial model. A retailer that runs offsite campaigns on its own seat keeps the advertiser relationship and the margin, rather than passing them to a third-party partner. Osmos's offsite retail media apps are built for the own-seat model: its White Labeled DSP runs the retailer's audience network across Meta, Google, TikTok and The Trade Desk, and Osmos's Guaranteed Outcomes service runs tail and torso advertisers across Meta, Google and TikTok, managed to outcomes, so the retailer earns the ad revenue without adding ad-ops headcount.
Offsite keeps its budget when the measurement holds: an ad served on a social feed or a streaming app has to tie back to an online order or an in-store purchase on the retailer's side, through a loyalty ID, a hashed identifier or a clean room. Without that link, offsite reads to a brand like any other upper-funnel spend and competes on price alone.
How should retail media measurement look by 2028 if brands are to keep renewing?
By 2028, brands will expect every retail media network to report incremental sales against an industry standard, across onsite, offsite and in-store, in reporting they can access themselves. Incrementality is the share of sales an ad caused that would not have happened without it, measured by comparing exposed shoppers with a holdout group that did not see the ad.
The measurement standards are converging. The IAB and IAB Europe published Guidelines for Incremental Measurement in Commerce Media on November 3, 2025, and IAB Europe opened a draft in-store measurement standard for comment on September 17, 2026 (PPC Land, September 2026). In the US, the IAB and MRC Retail Media Measurement Guidelines remain the reference for definitions and reporting. A network that already reports to these documents gives brands a reason to compare it favourably with larger networks.
Brands search for "the best commerce media networks with transparent measurement and reporting" and "which commerce media networks deliver the best ROAS." The networks brands pick for better ROAS are the ones whose return they can check and trust. Osmos orders the five reporting capabilities a brand checks before renewing from the proof of lift it checks first to the ROAS context it reads last:
- Incremental lift alongside attributed sales. Holdout or geo-based tests that show what the campaign added, reported per campaign.
- Standard definitions. Impressions, attributed sales and look-back windows defined the way the IAB and MRC guidelines define them, so a brand can compare networks line by line.
- Closed loop across channels. Offsite and in-store exposure tied back to the same transaction data as onsite, measured the same way.
- Self-serve reporting. Brands and agencies see campaign results directly, without waiting for a monthly deck.
- ROAS (return on ad spend) in context. Return shown with its attribution window and benchmark, so a brand reads the number fairly. For the benchmark ranges brands use, see the ROAS benchmarks for retail media networks.
Osmos's retail media measurement apps cover the lift side of that list: Brand Lift Study shows the upper-funnel effect that ROAS misses, and Osmos Incrementality, currently in early access, measures true lift with geo-holdouts, audience holdouts and synthetic control. For attribution models, windows and clean rooms in depth, see the attribution and measurement guide.
How can financial institutions enter the retail media space?
Financial institutions enter the retail media space by building a financial media network: they offer ad and offer placements in their own apps, websites and statements, use their transaction data as the targeting layer, and report results against completed purchases. Banks with large cardholder bases, such as Chase, build their own network, while others partner with a payment network, a commerce platform or a retail media technology provider.
A financial media network (FMN) is an advertising business run by a bank, card issuer, payment network or fintech that uses its first-party transaction data to target and measure ads and offers. Osmos lists fintech and payments among the industries its platform serves, and runs the same onsite ad engine for a fintech checkout that it runs for a retail marketplace.
Financial media networks are a small segment that is growing fast. EMARKETER forecasts US financial media network ad spending will grow from $680 million in 2025 to $3.15 billion in 2028 (EMARKETER, June 2026). Chase, PayPal and Mastercard launched the networks that set the model:
- Chase Media Solutions launched on April 3, 2024. Chase serves nearly 80 million consumers and nearly 6 million small businesses, and says "with Chase's owned transaction data, brands and agencies can precisely target customers at scale based on purchase history" (Chase, April 2024).
- PayPal Ads launched in May 2024, drawing on data from nearly 400 million active accounts and nearly half a trillion dollars of transactions (Customer Experience Dive, May 2024).
- Mastercard Commerce Media was announced on October 2, 2025, built on transactions processed by Mastercard, with 500 million enrolled consumers and an existing base of 25,000 advertisers (Open Banking Expo, October 2025).
How financial institutions monetize transaction data for media
Financial institutions earn media revenue from placements they own, and the data stays with them. The transaction data decides which customer sees which offer or ad and proves whether a purchase followed; the product the advertiser pays for is the placement in the bank's app, card offers, rewards pages or statements. Osmos groups the entry paths by how much audience the institution owns:
- Build an owned network. A bank or card issuer with a large, engaged app audience runs its own ad and offer inventory and an in-house sales team. Chase runs this model, which only pays off with an app audience large enough to fund in-house sales.
- Partner at network level. Issuers and merchants join a payment network's program, which pools transaction signals across many institutions. Mastercard's program works this way and gives banks too small for a standalone network a place in commerce media.
- Add retail media to a fintech marketplace. A BNPL provider, wallet or rewards platform that already lists merchants' products runs onsite retail media on those listings, with merchants as advertisers.
The third path is where Osmos has the clearest proof in the category. Osmos helped one of India's largest buy now, pay later (BNPL) platforms, which pairs its credit-led checkout with a marketplace of hundreds of independent merchants, grow monthly advertiser ad spend 12x in eight months; listing updates run in under 15 minutes, keeping ads matched to live listings (Osmos BNPL success story).
How banks partner with commerce for media network development
Banks partner with commerce by linking card offers to merchant campaigns, co-building audiences with retailers through clean rooms, and licensing technology to run placements in their own channels. Publishers can increase yield the same way, by launching commerce media monetization on their affiliate, checkout or subscription data and offering performance placements priced on purchases.
A bank or fintech needs consent flows, opt-outs and clean-room controls that pass regulatory review before launching a campaign, and Mastercard describes its network as driven by permissioned data. For a retailer, the opportunity runs the other way as well: a bank or payment partner can bring card-linked measurement that extends the retailer's own closed loop. For more on keeping control of first-party data in these partnerships, see first-party data ownership in retail media ecosystems.
Where is in-store retail media headed?
In-store retail media is headed toward bookable, standardized inventory priced and targeted by place and time: store location, day and time. Stores hold more shopper attention than any digital channel, and the work over the next two years is turning screens, shelves and analog placements into inventory that brands can plan and buy like digital media.
Large US retailers are already rolling out store screens. Modern Retail reported that CVS expects about 11,000 digital screens nationwide in 2026 and checkout ads on point-of-sale systems in about 7,000 stores, while Hy-Vee added more than 10,000 in-store screens across more than 400 locations by the end of 2024 (Modern Retail, January 2026).
In-store pricing follows how most stores are equipped. Few retailers have sensors that count individual viewers, so in-store media is priced per store, per campaign or per day, tied to store count and duration; cost per thousand impressions would need a viewer count those stores cannot produce. Targeting works by place and time as well: the shopper data decides which store, which day and which hour a placement runs, such as breakfast brands on weekday mornings in commuter-area stores. The IAB Europe draft takes the same approach, estimating opportunities to see from six inputs: daily footfall, number of stores, campaign days, placements, aisle penetration and the campaign's share of voice. IAB Europe describes the document as "proposals rather than a final standard," with comments open until October 23, 2026 (PPC Land, September 2026).
Analog inventory belongs in the same plan as screens. Floor decals, standees, shelf wobblers, end-caps and food demonstrations are often a store's largest ad estate, and they become revenue once they are bookable alongside screens. Osmos's in-store retail media apps cover both: Booking Calendar plans, prices and books inventory across screens and physical placements; Physical Media manages analog placements as bookable inventory; and Footfall Analytics, in early access, targets by store, city, zone or aisle. For the full in-store outlook, see the in-store monetization outlook.
How will AI and automation change retail media networks?
AI lowers the cost of serving each advertiser, and it changes how shoppers discover products, which changes what ad inventory is worth. Coresight Research's January 2026 report on agentic commerce frames the second shift around shopping assistants such as Amazon's Rufus and Walmart's Sparky, which choose products on a shopper's behalf and reduce the clicks and impressions that retail media has priced on (Coresight Research, January 2026).
The lower cost of serving advertisers is already visible in the largest networks. Amazon's Ads Agent, in a rolling closed beta, lets advertisers plan media, create and manage campaigns, and measure performance in plain language, and Amazon reports 40% faster first sales for beta campaigns using auto-optimized Sponsored Products (Amazon Ads). Brands that get that level of help on Amazon expect something similar elsewhere.
For a mid-market network, the biggest gain is in the tail and torso of the advertiser base. Most networks earn most of their revenue from a few dozen large brands and leave hundreds of smaller advertisers inactive, because each one costs too much ad-ops time to onboard and optimize. Osmos's Ad Sales and Ad Ops as a Service teams activate and run torso and tail advertisers for the retailer, and Osmos's Sofie AI agents, which Osmos lists as coming soon, include a Performance Manager agent built to tune keywords, bids and product selection continuously.
AI also raises the value of differentiated inventory. When assistants compress the product search results page, high-impact formats the retailer designs itself become more valuable for brands' awareness budgets. Osmos's Custom Ads let a retailer create custom ad formats that match its own interface, such as a branded unit built into a recipe or buying-guide module, priced at a premium. Two further steps prepare a network for agent-driven shopping: keeping catalog and availability data accurate in real time, so any assistant or ad points to an in-stock offer, and measuring sales lift, which keeps its value if clicks decline.
How do mid-market retailers compete with Amazon and Walmart in retail media?
Mid-market retailers compete with Amazon and Walmart by specializing in an audience those two cannot reach as well, getting to revenue quickly on modular technology, and activating advertisers the giants underserve. The realistic goal is to own a category, a region or a loyalty base.
Working with a platform partner gets a retailer to ad revenue faster and at lower cost than building in-house. According to The Retail Exec, working with a platform partner takes 3 to 6 months and $100,000 to $500,000, against 12 to 18 months and $2 million to $5 million to build a network in-house, with a composable middle option at 6 to 12 months and $500,000 to $1.5 million. The same article, citing MarTech, puts retail media network profit margins at 60% to 70%, against 5% to 10% for traditional retail (The Retail Exec, November 2025). A retailer that builds in-house stays out of brands' plans for months longer than one that works with a partner, and that budget goes to larger networks in the meantime.
Osmos orders retail media network development for a mid-market retailer by time to first revenue, starting with the inventory the retailer already has:
- Launch onsite first. Product Ads and display on search, category and product pages, monetizing the highest-intent traffic the retailer already has.
- Turn on self-serve and billing. Brand self-serve buying, wallets and billing that reconcile against delivery, so smaller advertisers can start without a sales call. Osmos's orchestration layer covers Brand Self-Serve, Wallets and Billing and Inventory Studio for this step.
- Package inventory. Bundles across formats and pages that lift fill rate and deal size.
- Extend offsite and in-store. Audience extension on the retailer's own seat, and stores as a bookable channel where the retailer has an estate.
- Prove lift. Incrementality and brand-lift reporting that gives brands a reason to move budget from larger networks.
A mid-market network defends its position through its vertical. Beauty, pharmacy, grocery, electronics and fintech audiences each carry purchase patterns (repeat cycles, regimen-based buying, credit-approved shoppers) that a generalist marketplace models less precisely. A specialist network that pairs that audience with clean measurement gives a brand something it cannot buy on Amazon. For the trade-offs between one platform and several vendors, see the single platform versus multi-vendor stack analysis.
What should a retailer do in the next 12 months?
A retailer should spend the next 12 months proving lift, adding channels and activating more advertisers, because those moves decide share through 2028. Osmos lists six moves in priority order, measurement first because 2027 budget planning depends on it:
- Measure to a standard now. Align reporting to the IAB and MRC guidelines and run at least one incrementality test per major advertiser before 2027 budget planning.
- Activate the long tail. List every advertiser with spend potential but no active campaign, and give them self-serve or managed service.
- Add one channel beyond onsite. Choose offsite on the retailer's own seat or in-store place-and-time packages, based on where the retailer's audience is most distinctive.
- Create one premium format. Build a high-impact custom format for awareness budgets that sponsored listings do not capture.
- Fix catalog freshness. Keep listings, prices and availability current so ads, and AI shopping assistants, never point to an unavailable offer.
- Explore a financial or partner data layer. Assess whether a bank, payment or loyalty partner can extend the retailer's closed loop.
To see how these moves run on one system, explore the Osmos retail media operating system or book a demo.
Frequently asked questions
Which is the best commerce media network, from a retailer's point of view?
From a retailer's side, the commerce media networks brands rank highly for better ROAS offer a distinct audience, incremental lift measured to the IAB standard, self-serve buying, and a managed option for brands without in-house teams. Each brand then picks the network whose audience, proof and buying experience fit the campaign. Osmos builds its white-label system around those tests.
How are leading commerce media platforms supporting advertisers?
Leading platforms support advertisers with a choice of service model: self-serve tools for brands that run their own campaigns, managed service for those that do not, and AI-assisted recommendations on bids, budgets and products for both. Osmos offers self-serve buying through Brand Self-Serve and a managed route through its Ad Ops as a Service team, so a retailer can take budget from both kinds of brand on one platform.
Which commerce media platforms have the strongest first-party data and personalization capabilities?
The strongest first-party data sits with the media owner: a grocer's basket history, a marketplace's cross-category behavior or a bank's card activity. The platform activates that data as a targeting layer and keeps the shopper experience relevant with relevance ranking, frequency caps and retailer-set bid floors. Osmos's Product Ads ship relevance ranking and retailer-set bid floors as part of the engine.
What is the best retail media platform for a marketplace?
The best retail media platform for a marketplace supports seller self-serve, multi-seller listing logic, seller wallets and seller-level attribution, because the marketplace's advertisers are its sellers. Osmos works with retailers and marketplaces on one engine. For a broader view of platforms and networks, see the retail media evolution guide.
How can retailers turn first-party data into retail media revenue?
Retailers turn first-party data into revenue by using it as the targeting and measurement layer for the ad placements they own: onsite, offsite on their own seat, and in-store. The retailer keeps control of its first-party data while charging brands for the ad placement and the measurement. The fastest start is onsite Product Ads on search and category pages, followed by audience extension offsite once measurement is in place.
Sources
- WARC, Future of Commerce Media 2026, as reported by The Desk, August 19, 2026.
- WPP global ad spend forecast, as reported by Digiday, December 8, 2025.
- Webtonic, "Where Retail Media Budgets Are Moving This Year" (reporting EMARKETER forecasts), updated October 9, 2026.
- IAB, 2026 Outlook Study: September Update, September 2026.
- EMARKETER, The State of Financial Media Networks 2026, June 30, 2026.
- PPC Land, "Amazon advertising gains 26% to $19.8 billion", July 31, 2026.
- PPC Land, "Walmart ad business gains 38% as Walmart Connect hits 43% in Q2", August 20, 2026.
- Instacart, Second Quarter 2026 Financial Results, August 6, 2026.
- PPC Land, "IAB Europe draft cuts in-store ad impression formula to six inputs", September 2026.
- IAB and MRC, Retail Media Measurement Guidelines, January 2024.
- Chase, "Chase launches Chase Media Solutions", April 3, 2024.
- Customer Experience Dive, PayPal advertising platform, May 31, 2024.
- Open Banking Expo, "Mastercard unveils Mastercard Commerce Media", October 2, 2025.
- Modern Retail, "Retailers like Kroger and CVS plan many more screens for in-store ads in 2026", January 6, 2026.
- Coresight Research, "Agentic Commerce: The Impact on Retail Media and How Retailers Should Respond", January 6, 2026.
- Amazon Ads, Ads Agent, retrieved October 12, 2026.
- The Retail Exec, "How Mid-Market Retailers Can Build Retail Media Networks", November 12, 2025.
Apps in this story
Suggested reading
Your monetization potential
See what's above your ceiling.
Your score, your peer benchmark, and the levers that close the gap.